How to Choose the Right Business Structure in India
Choosing the right business structure is an important step when starting a business in India. Understand the differences between sole proprietorship, partnership, LLP, OPC and Private Limited Company to make an informed decision based on your business goals, ownership, liability and future growth plans.
Starting a business is an exciting step, but before you begin accepting customers or investing money, there is one important decision to make: choosing the right business structure.
The structure you select affects how your business operates, who owns it, how profits are shared, what happens if the business faces losses, and which legal compliances you need to follow. It can also influence your ability to bring in partners, attract investors and expand your operations in the future.
For example, someone starting a small online store may have different requirements from an entrepreneur planning to establish a manufacturing company. Similarly, a consultant working independently may not need the same structure as a startup preparing to raise funds.
Understanding these differences before registration can help you make a decision that suits your business plans.
What Is a Business Structure?
A business structure is the legal form under which a business operates. It defines the relationship between the business owner and the business itself, including ownership, liability, management responsibilities and applicable compliance requirements.
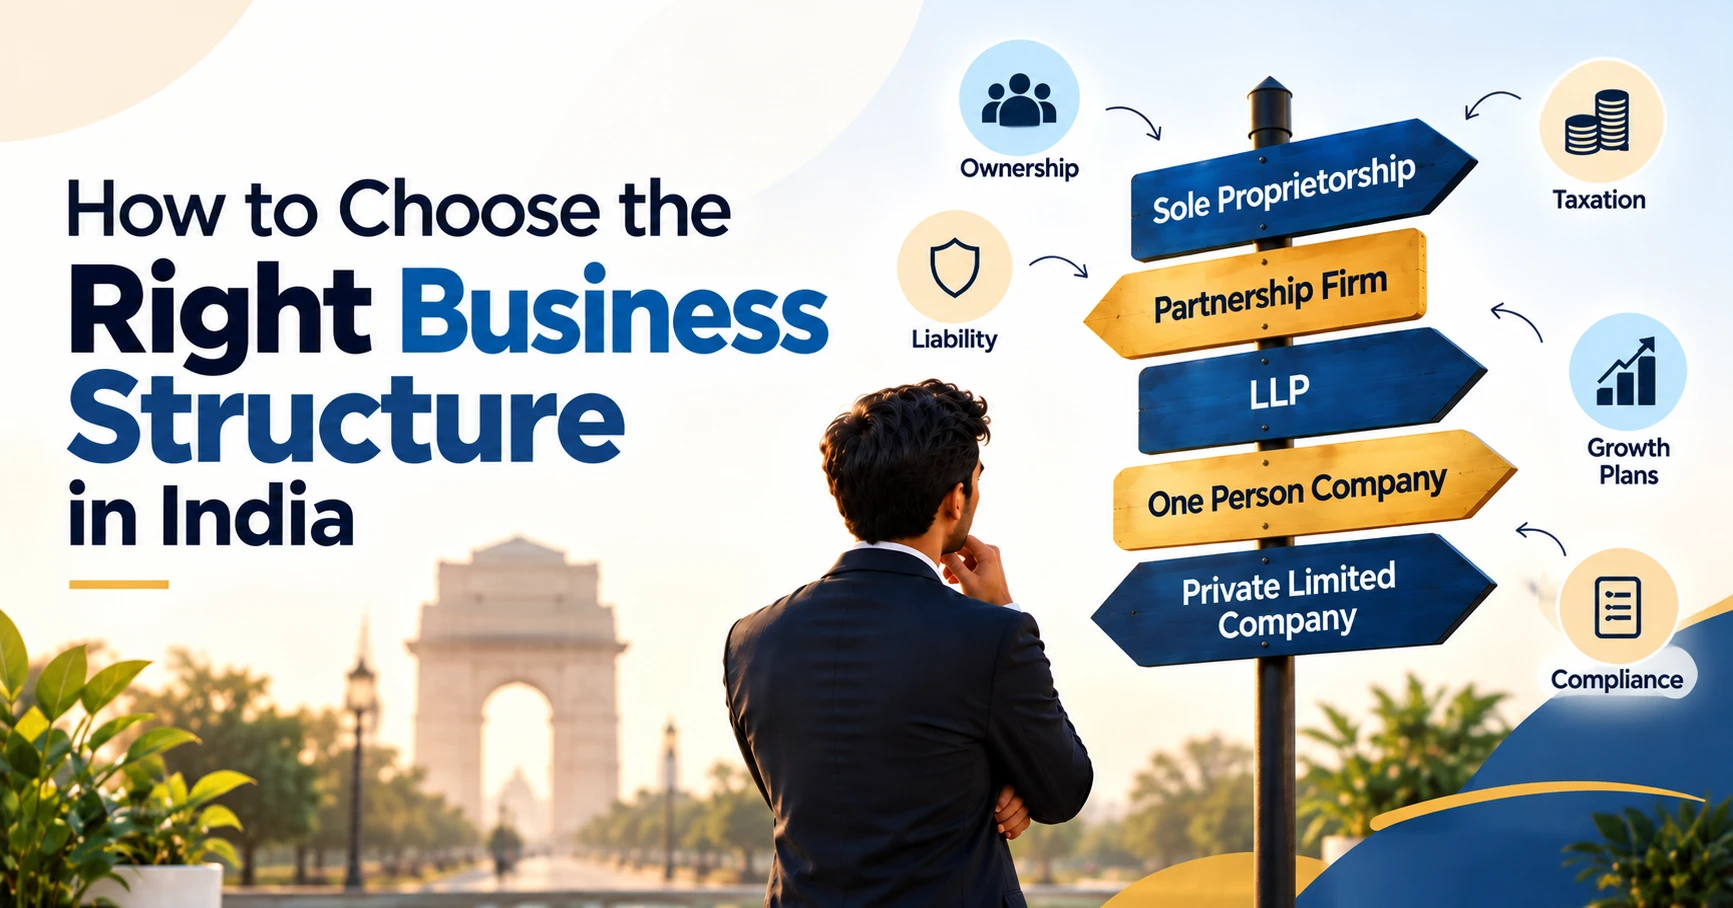
In India, entrepreneurs can choose from several structures, including Sole Proprietorship, Partnership Firm, Limited Liability Partnership (LLP), One Person Company (OPC) and Private Limited Company.
Each option serves different business needs. The right choice depends on the number of owners, the nature of the business, financial resources, risk exposure and long-term plans.
1. Sole Proprietorship
A Sole Proprietorship is one of the simplest ways for an individual to start a business. It is commonly used by freelancers, independent consultants, small retailers, home-based businesses and individual service providers.
The owner manages the business, makes decisions and receives the profits. The setup is generally straightforward compared with incorporating a company, although registrations and licences may still be required depending on the business activity.
One important point to understand is that a sole proprietorship does not have a separate legal identity from its owner. The proprietor is generally personally responsible for the business's debts and liabilities.
This structure may suit you if you are starting a small business independently, want direct control over daily operations and do not currently need multiple owners or equity investors.
For instance, a person selling products online or providing freelance services may consider a sole proprietorship, depending on their business requirements.
2. Partnership Firm
A Partnership Firm is suitable for people who want to run a business together. Partners contribute capital, skills, experience or other resources and agree to share profits according to the terms of their partnership agreement.
This structure is often considered for trading businesses, small enterprises, family businesses and service-based ventures.
A properly drafted partnership deed is important. It should explain each partner's role, capital contribution, profit-sharing ratio, decision-making authority and the procedure for handling disagreements or a partner's exit.
Traditional partnerships generally involve personal liability for the firm's obligations. This is an important consideration before entering into a partnership.
A Partnership Firm may be worth considering when two or more people want to work together under a traditional partnership arrangement and understand the associated responsibilities.
3. Limited Liability Partnership (LLP)
A Limited Liability Partnership combines elements of a partnership with a separate legal identity and limited liability for its partners, subject to applicable law.
An LLP is often considered by consultants, professional service providers, agencies and businesses operated by two or more partners. It allows partners to define their responsibilities and profit-sharing arrangements while maintaining a formal legal structure.
An LLP is registered under the Limited Liability Partnership Act, 2008. It must also meet applicable filing, accounting and other compliance requirements.
Unlike a traditional partnership, an LLP generally offers protection against personal liability for the obligations of the business. However, this protection is subject to legal exceptions, including circumstances involving a partner's own wrongful conduct or applicable fraud provisions.
If you want to start a business with another person and prefer a formal structure without adopting the conventional company model, an LLP may be an option to evaluate.
4. One Person Company (OPC)
A One Person Company is designed for an entrepreneur who wants to establish a company with a single member.
An OPC has a separate legal identity from its owner and generally provides limited liability, subject to applicable legal exceptions. It can be useful for an individual who wants to operate through a formal corporate structure rather than a sole proprietorship.
However, an OPC must comply with the applicable provisions of the Companies Act, 2013, including statutory filings and record-keeping requirements. Eligibility, nomination and conversion rules should also be reviewed before incorporation.
This structure may suit an individual entrepreneur who wants to retain ownership while building a business with a formal corporate identity.
Before choosing an OPC, consider whether you may need additional shareholders or external equity investment in the future, as these plans can affect the structure you eventually require.
5. Private Limited Company
A Private Limited Company is a popular option for startups and businesses planning to expand their operations, establish a formal corporate presence or bring in investors.
It is incorporated under the Companies Act, 2013 and has a legal identity separate from its shareholders. Ownership is represented through shares, while the company's affairs are managed through its directors in accordance with applicable law.
A Private Limited Company generally provides limited liability to its shareholders, subject to the relevant legal exceptions.
This structure may be suitable for technology startups, manufacturing units, e-commerce businesses, food brands, trading companies and other ventures with long-term growth plans.
For example, an entrepreneur planning to launch a consumer product, build a team, expand into multiple markets and seek investment may consider a Private Limited Company.
However, incorporation is only the beginning. Companies must meet applicable statutory requirements, maintain records and complete prescribed filings. These responsibilities should be considered alongside the benefits of the structure.
Factors to Consider Before Choosing a Business Structure
Choosing a business structure involves more than comparing registration costs. It is important to understand how each option fits your actual business requirements.
Number of Owners
Start by identifying who will own the business.
If you are working alone, you may consider a Sole Proprietorship or OPC. If you are starting with partners, a Partnership Firm or LLP may be relevant. If you intend to create a company with shareholding arrangements, a Private Limited Company may be worth considering.
Your ownership plans should be clear before you begin the registration process.
Personal Liability
Consider the financial risks associated with your business.
A business may face unpaid invoices, contractual disputes, loans or other liabilities. Under a sole proprietorship, the owner is generally personally responsible for business obligations. Partners in a traditional partnership also generally face personal liability.
An LLP or company usually provides a degree of separation between personal and business liabilities, subject to applicable law.
Understanding this distinction is particularly important if your business involves manufacturing, significant investments, employees, credit transactions or long-term contracts.
Taxation
Tax treatment differs across business structures. The applicable tax rates, deductions, filing obligations and treatment of profits depend on the legal form of the business and the circumstances involved.
For this reason, it is better to evaluate taxation based on your expected revenue, expenses, profits and plans for withdrawing or reinvesting earnings.
A structure that appears less expensive initially may not necessarily be the most suitable option for your overall financial position. Consider consulting a qualified tax professional before making the final decision.
Future Growth and Investment
Think about your business plans for the next three to five years.
Do you intend to remain a small owner-managed business, hire employees, open new locations, expand across India or raise funds from investors?
A Sole Proprietorship may be adequate for a straightforward individual venture. An LLP may suit a partner-managed business, while a Private Limited Company may be relevant when share-based ownership and equity investment are important.
Choosing a structure with your future plans in mind can help reduce the need for major changes later.
Compliance Requirements
Different structures have different legal and administrative responsibilities.
Depending on the structure and business activity, you may need to maintain accounts, file income tax returns, submit annual returns, maintain statutory records or comply with other regulatory requirements.
Before registering, understand the ongoing responsibilities involved. Do not focus only on the initial registration process or professional fees.
Nature of the Business
Your business activity also matters.
A consultancy, online retail business, food manufacturing unit and export business may have different operational and regulatory requirements.
For example, a food business may need an appropriate FSSAI registration or licence. GST registration may be required depending on the applicable provisions, while an Importer Exporter Code may be relevant for import and export activities.
These registrations and licences are separate from the business structure itself. Incorporating a company or registering an LLP does not automatically provide every approval needed to operate.
Which Business Structure Should You Consider?
The appropriate structure depends on how you plan to run your business.
If you are a freelancer or an individual service provider, a Sole Proprietorship may meet your current needs.
If you are starting a business with another person and want a traditional partnership arrangement, a Partnership Firm may be worth evaluating. If limited liability and a separate legal identity are important to the partners, an LLP may be another option.
If you are working alone but want to establish a formal company, you may consider an OPC. If your plans involve multiple shareholders, structured ownership or potential equity investment, a Private Limited Company may be more relevant.
These are general examples, not fixed rules. Your business risks, ownership arrangements, financial position and long-term objectives should guide the final decision.
Can You Change Your Business Structure Later?
In certain circumstances, it is possible to move from one business structure to another. However, the process depends on the existing structure and the intended destination.
A change may involve legal documentation, tax implications, asset transfers, contractual arrangements, licences and other compliance requirements.
For example, a business that begins on a small scale may later require a structure that supports additional owners or investment. Planning for this possibility early can make future decisions easier.
If you expect your business to grow significantly, discuss the available options with a professional before registration.
Common Mistakes to Avoid
Many entrepreneurs focus mainly on the cost of registration when selecting a business structure. While cost is important, it should not be the only consideration.
Avoid choosing a structure without understanding the liability involved. Do not select an option simply because another business uses it. Make sure the responsibilities of partners are documented clearly, and understand the compliance requirements that apply after registration.
It is also important not to assume that registering a business automatically completes all legal formalities. Depending on your activities, additional tax registrations, licences or permissions may be necessary.
Taking the time to understand these requirements can help you avoid unnecessary complications as your business develops.
Final Thoughts
Choosing the right business structure is an important part of starting a business in India. It affects ownership, liability, compliance responsibilities and the way you plan for future growth.
A Sole Proprietorship, Partnership Firm, LLP, OPC or Private Limited Company can serve different purposes. The right option is the one that fits your business activity, ownership plans, financial circumstances and long-term objectives.
Before proceeding with registration, review the available structures carefully and understand the legal and financial responsibilities attached to each one.
At E-Incorp Elite, we assist entrepreneurs and business owners with business registration and related compliance services. Our aim is to help you understand the registration process and the requirements relevant to setting up your business in India.
Visit www.e-incorpelite.com to learn more about our services and take the next step towards establishing your business.
Disclaimer: This article is intended for general informational purposes only and does not constitute legal, tax or financial advice. Applicable laws, eligibility conditions and compliance requirements should be verified before making a registration decision.
Need help with your business?
Our team can guide you through registration, compliance, taxation and other business requirements.